

JurnalPost.com — Determining the selling price is one of the most critical decisions for Micro, Small, and Medium Enterprises (MSMEs). The price set must not only attract consumers but also account for all costs incurred during the production process. Without precise calculations, a business risks operating at a loss, even if its products are popular in the market.
In running a business, various cost components must be considered, ranging from raw materials and packaging to utility expenses like gas or electricity, and even rent. All these expenditures must be recorded so that business owners understand the capital required to produce a single unit of their product.
Unfortunately, many business owners still determine selling prices based on estimates or by following competitors' prices. In reality, every business has a different cost structure, meaning that applying the same price does not necessarily yield equivalent profits.
Therefore, understanding the Cost of Goods Sold (COGS) is a fundamental pillar of MSME financial management.
The Importance of Calculating the Cost of Goods Sold
The Cost of Goods Sold (COGS) is the calculation of the expenses required to produce a specific item or product. By calculating COGS, business owners can determine the production cost per unit and use it as a basis for setting the selling price.
This calculation also helps MSME owners understand the relationship between production costs, selling prices, and potential profit margins.
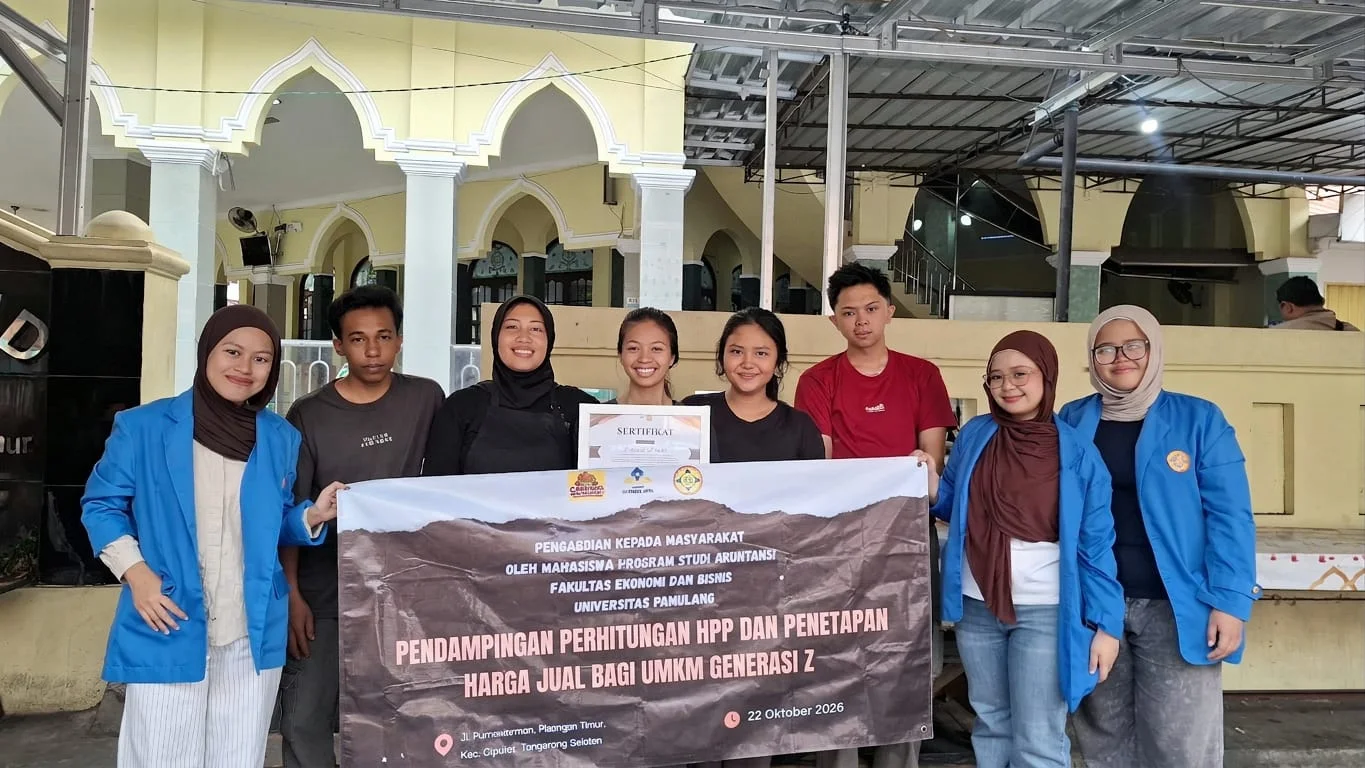
The importance of cost recording and COGS calculation was highlighted during a mentoring session for five MSMEs located on Jalan Purnawarman, Pisangan Timur, East Ciputat District, South Tangerang City, on October 22, 2026.
The mentoring covered five types of businesses: corndogs, fresh orange juice, burgers, iced tea, and brass key duplication services. Each business has unique production cost requirements and pricing strategies.
Production Cost Calculation Results for Five MSMEs
Based on data collected during the mentoring, the corndog business incurred a total production cost of Rp660,000 to produce 60 skewers. Consequently, the COGS per skewer reached Rp11,000. The product is sold for Rp13,000, leaving a margin of Rp2,000 per skewer between the selling price and the COGS.
Meanwhile, the fresh orange juice business recorded a total production cost of Rp200,000 to produce 50 cups. Based on this calculation, the COGS per cup is Rp4,000, while the selling price is set at Rp5,000.
For the burger business, production costs reached Rp156,000 to produce 13 burgers. The COGS per burger is Rp12,000, while the selling price is Rp15,000 per unit.
A different calculation was seen in the iced tea business. With a total production cost of Rp143,000 to produce 55 cups, the COGS per cup reached approximately Rp2,600. The product is then marketed at a price of Rp5,000 per cup.
The brass key duplication service recorded production costs of Rp120,000 to produce 10 items. The COGS per item is Rp12,000, while the selling price reaches Rp35,000.
Interestingly, the price for the key duplication is above the price of similar products in the vicinity, which is reported to be around Rp30,000.
This difference demonstrates that setting a selling price is not only related to the magnitude of production costs but is also influenced by competitive conditions and the value offered to consumers.
Selling Prices Must Consider Market Conditions
Every MSME owner needs to understand that a higher selling price compared to competitors is not always a wrong decision. However, price differences should be accompanied by reasons that are acceptable to consumers.
For example, the product or service offered may have better quality, more meticulous workmanship, or service that provides added value to the customer.
Conversely, setting prices too low without accounting for production costs can also create problems for business sustainability.
Prices that appear competitive may not necessarily cover all operational costs. If this condition persists, business owners may struggle to maintain their production activities.
Another point to note is that the difference between the selling price and the COGS cannot be immediately considered net profit.
If there are still costs that have not been included in the calculation, such as other operational expenses, the profit seen from sales results does not necessarily reflect the overall financial condition of the business.
Therefore, complete and organized cost recording is a crucial part of determining a more realistic selling price.
Simple Financial Recording Can Be a First Step
Managing MSME finances does not necessarily have to start with the use of complex accounting applications or systems.
Business owners can utilize notebooks or simple spreadsheets to document raw material purchases, production costs, the quantity of goods produced, and revenue from sales.
The most important thing is consistency in recording and updating information when cost changes occur.
For example, an increase in raw material prices can affect a product's COGS. If such changes are not accounted for, business owners risk maintaining a selling price that is no longer aligned with their production costs.
Through regular recording, MSME owners can evaluate expenses, identify the largest cost components, and consider price adjustments if necessary.
In addition to paying attention to internal costs, business owners also need to observe market developments, including public purchasing power, competitor prices, and the quality of goods or services offered.
Thus, pricing can be done in a more measurable way without always having to follow the lowest price in the market.
MSME Mentoring Needs to Encourage Sustainable Implementation
The results of the mentoring for the five MSMEs in East Ciputat provide an overview of the importance of understanding production costs in business decision-making.
Although this data cannot be used to represent the entire condition of MSMEs in Indonesia, the differences in cost structures among the five businesses show that each type of business requires a calculation approach tailored to its product characteristics.
Mentoring for MSME owners, therefore, should not only focus on introducing the COGS formula but also needs to encourage its application in daily business activities.
Business owners need to get into the habit of recording costs routinely, evaluating sales results, and understanding that the volume of products sold is not necessarily proportional to the profit earned.
Ultimately, business success is not determined solely by the ability to attract customers and increase sales. Good cost management is also a vital factor in maintaining business continuity.
Through consistent financial recording, careful COGS calculation, and pricing that aligns with market conditions, MSME owners have a stronger foundation to manage their businesses, protect profits, and face competition sustainably.



Comments 0
Write a Comment Share your response