

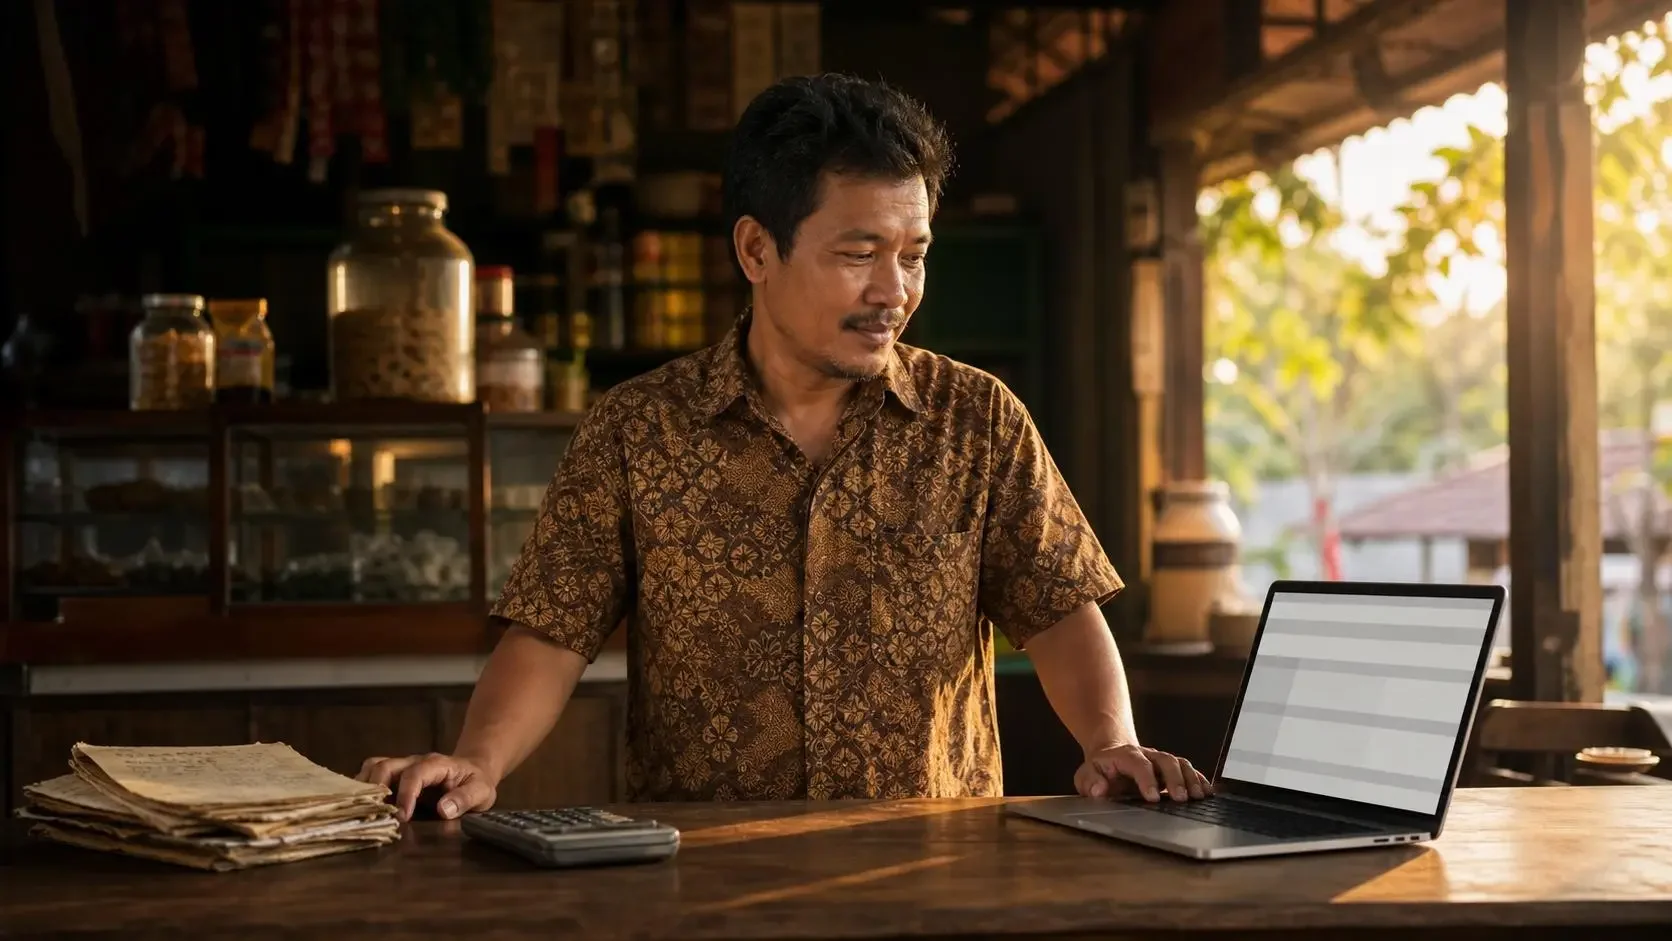
JurnalPost.com - The evolution of information technology has brought significant changes to how business owners manage their operations, including micro, small, and medium-sized enterprises (SMEs). One such shift is the adoption of financial and accounting information systems to record transactions, manage cash flow, and provide the data necessary for informed decision-making.
For SME owners, financial management is a critical aspect of maintaining business viability. However, challenges persist when transactions are recorded manually. Calculation errors, delays in report preparation, and difficulties in monitoring financial health can negatively impact business decisions.
In such situations, a Financial and Accounting Information System (FAIS) can serve as a solution to help business owners generate more accurate, structured, and timely information.
Understanding Financial and Accounting Information Systems
A Financial and Accounting Information System is a system used to collect, record, store, process, and present financial transaction data into information that is useful for organizational management.
According to Romney and Steinbart (2018), an accounting information system consists of six primary components: human resources, procedures and instructions, data, software, information technology infrastructure, and internal controls and security.
These six components are interconnected to ensure that the financial information processing cycle functions effectively.
The implementation of this system is not reserved solely for large corporations. SME owners can also leverage it to understand their business's financial condition, evaluate business activities, and determine development strategies.
For example, a retail business owner can use sales data to identify which products are most popular with customers. Meanwhile, inventory and purchasing information can help determine when items need to be reordered.
Thus, financial information functions not only as a record of transactions but also as a foundation for making decisions.
Five Transaction Cycles in Financial Management
In business operations, a Financial and Accounting Information System processes data from five primary transaction cycles.
First, the revenue cycle, which includes sales activities, cash receipts, and accounts receivable management. Information from this cycle can be used to evaluate sales performance and determine customer payment policies.
Second, the expenditure cycle, which relates to purchasing goods, payments to suppliers, and accounts payable management. Through this information, SMEs can plan purchasing needs and maintain cash availability.
Third, the production cycle, which covers the use of raw materials, labor, and production operational costs. This information helps business owners calculate the cost of goods sold and determine appropriate selling prices.
Fourth, the human resources cycle, which deals with employee attendance, payroll, and labor costs. The resulting data can be used as a consideration in managing workforce requirements.
Fifth, the financial and reporting cycle, which includes cash management, funding, investment, and the preparation of financial statements. This information helps business owners evaluate their overall financial condition.
These five cycles demonstrate that every business activity is linked to financial information.
The Role of FAIS in Business Decision-Making
Organizational decision-making is generally categorized into three levels: operational, tactical, and strategic.
At the operational level, financial information is used to support day-to-day decisions. Examples include determining debt payment schedules, collecting overdue receivables, or reordering inventory that is running low.
At the tactical level, information is used to develop medium-term business plans. Business owners can compare budgets with actual expenditures, evaluate the profitability of each product, and adjust pricing strategies.
Meanwhile, at the strategic level, financial statements serve as a key consideration when business owners plan to expand, purchase new equipment, or seek funding sources.
Using the right information can help business owners understand the risks and opportunities associated with every decision.
However, the existence of an information system does not automatically guarantee good decisions. The user's ability to read and interpret financial reports remains a crucial factor.
Research Findings on FAIS and SME Performance
The relationship between the use of accounting information systems and SME performance has been discussed in numerous studies in Indonesia.
Research by Terisiana et al. (2023) on SMEs in the Kuta Utara District shows that the use of accounting information systems has a positive influence on financial performance. The study also found a positive influence from the adoption of electronic commerce or e-commerce.
Research by Prasasti and Triyanto (2023) on garment SMEs in Surakarta City indicates that the implementation and utilization of accounting information systems significantly affect business performance. However, the understanding of accounting information systems did not show a significant influence in that study.
Other findings were presented by Irman et al. (2025) through a study of SMEs in Pekanbaru City. The results show a positive influence of accounting information systems on financial performance, but improvements in financial performance do not automatically correlate with business growth.
Meanwhile, Puspitasari and Ma'sum (2025), in their study of SMEs in Pati Regency, found that the use of accounting information systems and the understanding of financial information have a positive effect on performance. The understanding of financial information was also found to act as a moderating variable.
In general, these four studies demonstrate a positive relationship between the utilization of accounting information systems and SME performance.
However, the differing research results regarding user understanding indicate that the success of system implementation must be viewed from various aspects. Furthermore, most of these findings are based on questionnaire-based research and therefore do not necessarily prove a causal relationship.
The Importance of Internal Control and Information Security
The implementation of financial information systems must also be accompanied by sound internal controls.
Internal control aims to ensure that transactions are recorded correctly, information is reliable, and business assets are protected from errors and misuse.
In practice, these controls can be implemented through the separation of duties between those recording transactions and those handling cash, authorizing specific transactions, restricting access to data, and performing regular backups of financial information.
For SME owners, these steps can be implemented gradually according to the needs and capabilities of the business.
Even the most sophisticated accounting application will not provide maximum benefits if the data entered is incorrect or if the user does not understand the management procedures.
Steps for Implementing FAIS for SMEs
Implementing a Financial and Accounting Information System does not have to begin with expensive or complex technology.
SME owners can start by getting into the habit of recording all transactions regularly, separating personal and business finances, and preparing simple financial statements.
Subsequently, the use of recording applications can be adjusted to the scale of the business and the capabilities of the human resources.
Report preparation can also refer to the Financial Accounting Standards for Micro, Small, and Medium Entities (SAK EMKM), which are designed to support financial reporting for small-scale entities.
In addition to the use of technology, training on transaction recording and understanding financial statements needs to be prioritized.
By understanding the information generated, business owners can use financial statements as a basis for business evaluation and planning.
Conclusion
Financial and Accounting Information Systems play a vital role in helping SMEs manage transactions and provide information for decision-making.
Through structured data processing, business owners can gain insights into revenue, expenses, production costs, cash flow, and overall financial condition.
A review of four previous studies shows that the utilization of accounting information systems generally has a positive relationship with SME performance. However, the success of its implementation remains influenced by user capability, information quality, and internal controls.
Therefore, the utilization of FAIS should not be viewed merely as an effort to digitize record-keeping, but as part of a more planned, transparent, and sustainable business management strategy.
Comments 0
Write a Comment Share your response