

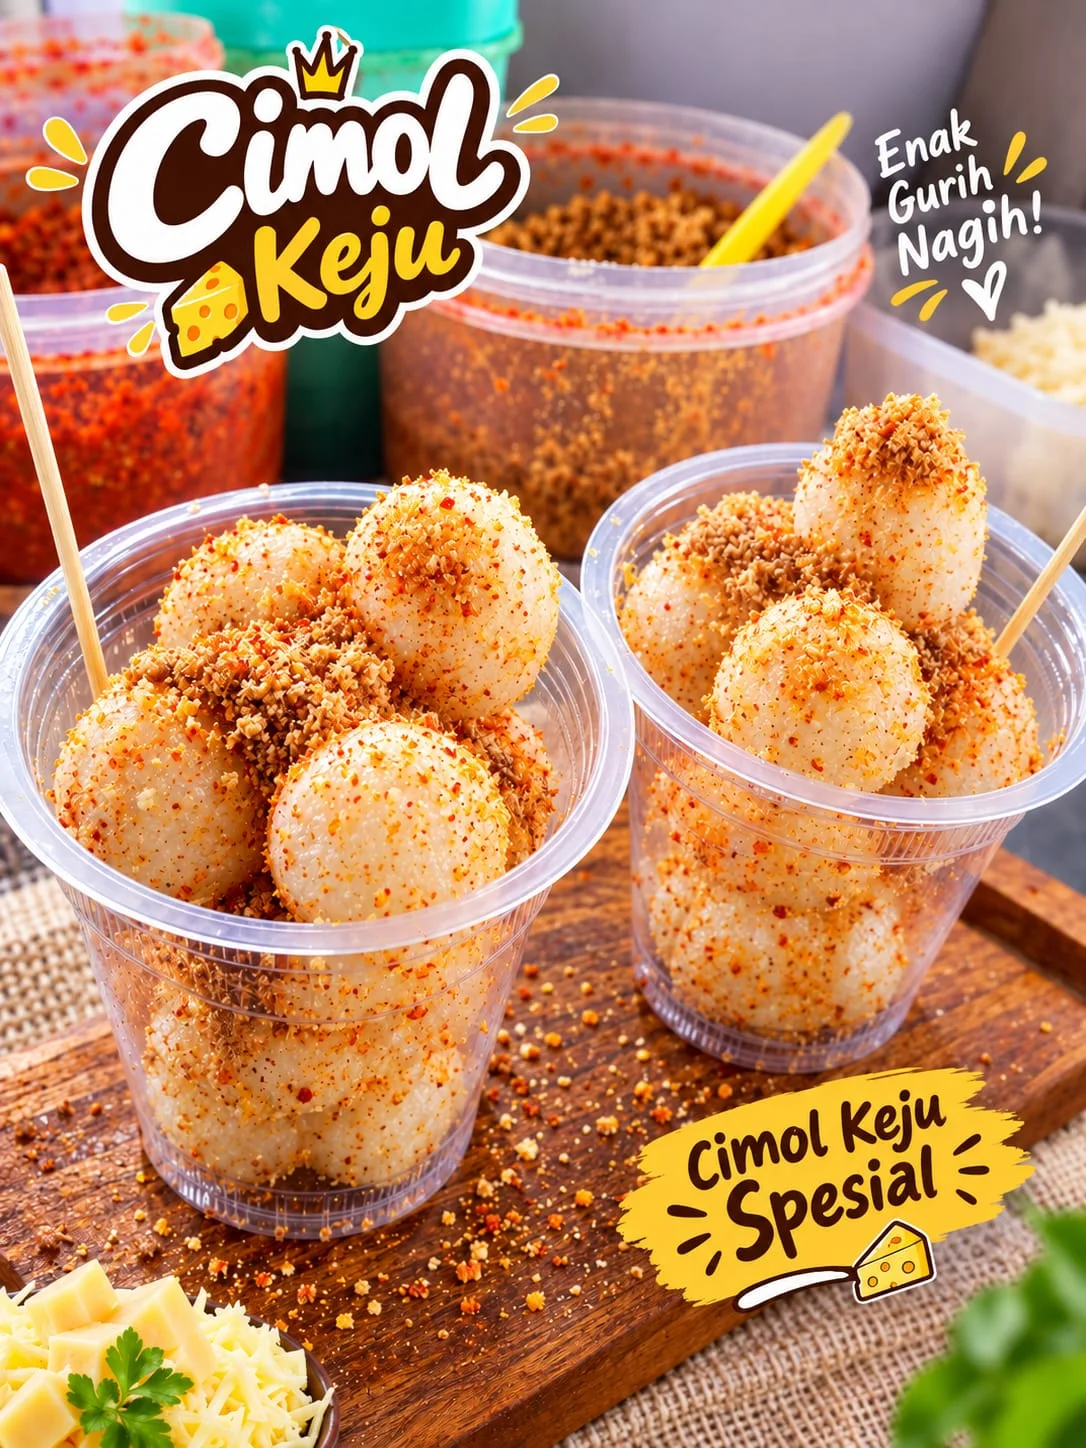
CIREBON, JurnalPost.com – Tapioca-based snack businesses continue to be an attractive option for micro-entrepreneurs. Beyond the fact that raw materials are relatively easy to source, tapioca products can be developed into various affordable snack options.
One product capitalizing on this opportunity is Cipak Koceak, a savory and spicy snack marketed at IDR 10,000 per pack.
The business is managed by a husband-and-wife team, Mr. Denni and Mrs. Rosela, who also operate the Ketoprak Sedap Malam culinary business in the Sunyaragi area, Kesambi District, Cirebon City, West Java.
The potential for developing the Cipak Koceak business became the subject of a feasibility study conducted by students from the Management Study Program, Faculty of Economics and Business, Universitas Swadaya Gunung Jati (UGJ) Cirebon.
The study was conducted to understand market opportunities, capital requirements, production cost structures, and the potential profits that could be earned if the business is operated consistently.
Based on financial simulations, the Cipak Koceak business has the potential to generate an operating profit of approximately IDR 4,050,000 per month, assuming sales reach 50 packs per day.
However, this figure is a calculation based on a set of assumptions, not the actual profit recorded in the business's financial statements.
Market Opportunities for Cipak Koceak at IDR 10,000
The selling price is a crucial factor in determining the competitiveness of snack products, especially for consumers who prioritize affordability.
At a price of IDR 10,000 per pack, Cipak Koceak has the opportunity to target various consumer groups, ranging from students and workers to the general public who enjoy spicy food.
In addition to direct sales, social media marketing can be an alternative for introducing the product to a wider consumer base.
Promotions can be carried out by displaying product photos, pricing information, spice level variations, and ordering services.
Nevertheless, sales success is not determined by price alone. Consistency in taste, hygiene in the production process, quality of raw materials, and customer service also determine the business's ability to retain buyers.
Capital and Production Cost Analysis
Based on information from the business owners, daily operational capital requirements for Cipak Koceak range from IDR 300,000 to IDR 500,000.
This amount serves as an estimate of the funds needed to carry out daily production activities.
In the business feasibility study simulation, the selling price is set at IDR 10,000 per pack, while variable production costs are estimated to reach IDR 7,000 per pack.
The details of these estimated costs include:
| Cost component | Estimate per pack |
|---|---|
| Tapioca and main ingredients | IDR 2,000 |
| Spices, chili, and seasonings | IDR 1,500 |
| Oil and complementary ingredients | IDR 1,500 |
| Packaging | IDR 1,000 |
| Gas, tissues, and other production costs | IDR 1,000 |
| Total variable costs | IDR 7,000 |
With this cost structure, each pack of Cipak Koceak provides a contribution margin of IDR 3,000 before fixed costs are deducted.
If the business produces 50 packs per day, the variable cost requirement is estimated to reach IDR 350,000. This amount remains within the daily operational capital range provided by the business owner.
This calculation does not yet use actual purchase records and production results, so it still needs to be verified through business financial records.
Monthly Profit Simulation for Cipak Koceak
To determine the profit potential, the study uses an assumption of sales of 50 packs per day for 30 days.
At a price of IDR 10,000 per pack, the revenue that can be obtained reaches IDR 500,000 per day or IDR 15,000,000 in one month.
Meanwhile, variable production costs are estimated at IDR 10,500,000 per month.
If fixed costs are assumed to be IDR 450,000 per month, the calculation results are as follows:
| Component | Monthly value |
|---|---|
| Sales | 1,500 packs |
| Turnover | IDR 15,000,000 |
| Variable production costs | IDR 10,500,000 |
| Contribution margin | IDR 4,500,000 |
| Fixed costs | IDR 450,000 |
| Simulated business profit | IDR 4,050,000 |
Thus, the Cipak Koceak business mathematically has the potential to earn a profit of IDR 4.05 million per month if all sales and cost assumptions are met.
This figure does not account for owner wages, equipment depreciation, taxes, and other expenses that may arise during operational activities.
Therefore, the actual net profit may differ from the simulation results.
Break-Even Point Estimated at 150 Packs per Month
In addition to calculating profit potential, this study also analyzes the break-even point or Break-Even Point (BEP).
The break-even point is the condition where business revenue is able to cover all calculated costs, meaning the business has not yet generated a profit or loss.
With fixed costs of IDR 450,000 per month and a contribution margin of IDR 3,000 per pack, the break-even point is calculated using the formula:
BEP = Fixed Costs ÷ (Selling Price − Variable Cost per Pack)
IDR 450,000 ÷ (IDR 10,000 − IDR 7,000) = 150 packs.
These results indicate that Cipak Koceak requires sales of approximately 150 packs per month, or an average of five packs per day, to cover costs in this simple calculation model.
If sales are able to reach 50 packs per day, that volume is about ten times the simulated break-even point.
However, the low break-even point in the simulation is heavily influenced by the amount of fixed costs used. If labor wages, equipment depreciation, and other expenses are included, the sales required to reach the break-even point may increase.
Risks of Rising Raw Material Prices and Declining Customer Numbers
Like other culinary businesses, Cipak Koceak faces the risks of changing raw material prices and fluctuations in consumer demand.
Increases in the price of flour, chili, cooking oil, or other complementary ingredients can increase production costs and reduce profits.
In a sensitivity simulation, an increase in variable production costs of 10 percent from IDR 7,000 to IDR 7,700 per pack would reduce monthly business profit from IDR 4,050,000 to approximately IDR 3,000,000, assuming the sales volume remains 1,500 packs.
Conversely, if the number of buyers drops by 20 percent so that sales become 1,200 packs per month, business profit is estimated to decrease to IDR 3,150,000 if the cost per pack remains unchanged.
These calculations demonstrate the importance of maintaining profit margins through cost control and inventory management.
Business owners can evaluate supplier prices, maintain consistency in product size, reduce waste, and track changes in the number of buyers.
Adjustments to the selling price can also be considered if cost increases persist, while still paying attention to consumer purchasing power.
Three-Year Business Development Projection
This study also compiles business development projections based on three scenarios: optimistic, moderate, and pessimistic.
In the optimistic scenario, sales volume is assumed to increase by 10 percent each year. With the selling price, variable cost per pack, and fixed costs considered unchanged, the monthly profit in the third year is projected to reach IDR 4,995,000.
In the moderate scenario with a sales volume growth of 5 percent per year, the monthly profit in the third year is estimated at IDR 4,511,250.
Meanwhile, in the pessimistic scenario where sales volume drops by 5 percent each year, the monthly profit in the third year is projected to be around IDR 3,611,250.
All these projections are illustrative. Changes in market conditions, increases in raw material costs, business competition, and changes in consumer habits can affect the actual results.
Legality and the Importance of Financial Record-Keeping for MSMEs
The aspect of legality is also a concern in the Cipak Koceak business feasibility study.
Based on business information, the owner has a Business Identification Number (NIB) issued on 12 July 2023 with a micro-enterprise classification.
The owner also stated that the business has a halal certificate and meets relevant food safety requirements. However, supporting documents other than the NIB information still require further examination to ensure their status and scope of legality.
In terms of financial management, recording daily transactions is an important step to assess the business's condition more accurately.
MSME players need to separate business funds from personal finances, record raw material expenses, calculate the number of products made and sold, and monitor inventory.
Recording for 14 to 30 days can be an initial step to obtain an overview of turnover, production costs, and actual profit.
This data can then be used to improve the calculation of the cost of goods sold, determine sales targets, and prepare business development plans.
Promising Business Potential, but Needs Verification
The study results show that Cipak Koceak has the potential to be developed as a snack business with an affordable price.
A profit simulation of IDR 4.05 million per month and a break-even point of 150 packs per month provide an initial overview of business opportunities if sales targets and cost control can be achieved.
However, these calculation results are not sufficient to state that the business has generated that much profit in practice.
The final feasibility assessment still requires actual sales data, details of material purchases, calculation of all costs, and examination of supporting documents.
Through more organized record-keeping and consistent business management, Cipak Koceak has the opportunity to strengthen its competitiveness in the local snack market.
This study also shows that MSME development is not enough just by relying on products that consumers are interested in. The ability to calculate costs, maintain margins, and make decisions based on data is an important part of building a sustainable business.
About the Author
Huda Fadhlunnisa is a student of the Management Study Program, Faculty of Economics and Business, Universitas Swadaya Gunung Jati, Cirebon.
This article was developed from a Business Feasibility Study course assignment under the guidance of Sandi Nasrudin Wibowo, S.E., M.M., based on field studies and interviews with the Cipak Koceak business owners, Mr. Denni and Mrs. Rosela.
Note: All calculations of COGS, sales volume, fixed costs, break-even point, profit, and projections in the article are academic simulations, not actual financial reports of the Cipak Koceak business.
Comments 0
Write a Comment Share your response