

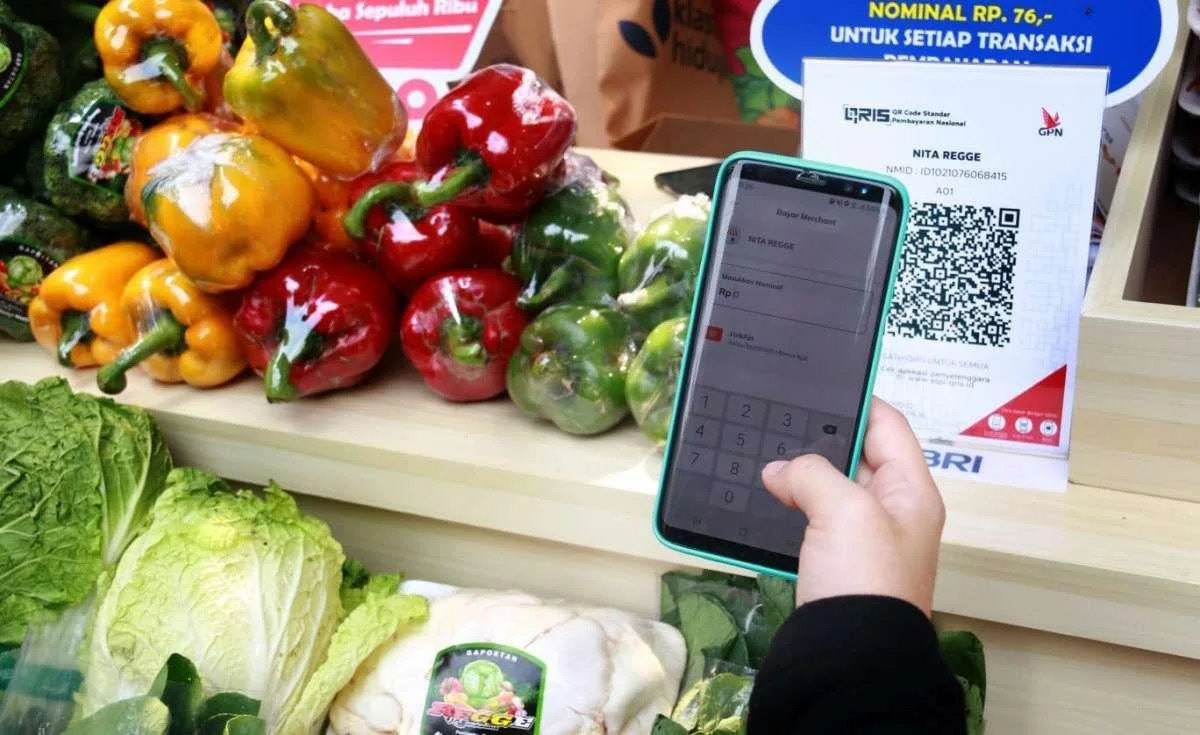
JurnalPost.com - The development of digital payment systems in Indonesia has shown rapid progress in recent years. The presence of various digital wallet platforms (e-wallets), the Quick Response Code Indonesian Standard (QRIS), electronic commerce (e-commerce), and paylater services have significantly changed the way people conduct transactions. Economic activities that previously required face-to-face meetings and cash payments can now be completed in seconds via smartphone.
According to Bank Indonesia (BI) data, the nominal value of digital banking transactions throughout 2023 reached IDR 58,478.24 trillion, a 13.48 percent increase from the previous year. Meanwhile, the Financial Services Authority (OJK) recorded that the outstanding credit for Buy Now Pay Later (BNPL) services from banks reached IDR 18.01 trillion in July 2024. In the same period, BNPL financing through finance companies was recorded at IDR 7.81 trillion.
This development highlights the growing role of technology in supporting the public's economic activities. From buying food and paying monthly bills to meeting daily needs, various transactions can now be performed more practically and efficiently.
However, behind this convenience lie several challenges that must be addressed, especially when viewed through the perspective of Islamic law. Ambiguity in contracts (gharar), potential usury (riba) practices, rising consumerist behavior due to easy access to financing, and the threats of fraud and personal data breaches are issues that cannot be ignored.
So, has all this convenience in digital transactions provided benefits that align with Sharia principles?
This question is important to examine through the approach of Maqashid Syariah, which is the primary objective of implementing Islamic law to realize public welfare and prevent harm to humanity.
Digital Transactions in the Perspective of Maqashid Syariah
Maqashid Syariah is a concept that places human welfare as the main goal of implementing Islamic law. One of its important principles is hifzh al-mal, which means guarding and protecting wealth from loss, misuse, or transactions that have the potential to cause harm.
In the context of digital transactions, the principle of hifzh al-mal has very strong relevance. Financial technology should not only offer speed and convenience but also provide guarantees of security, justice, and protection of user rights.
In Islamic jurisprudence (fiqh muamalah), the basic rule for a transaction is that it is permissible as long as it does not conflict with Sharia provisions. This means that the use of digital wallets, marketplaces, QRIS, or digital financing services cannot be immediately declared contrary to Islamic teachings simply because they use modern technology.
The assessment of a transaction must consider the contract used, the payment mechanism, fee provisions, and the possibility of elements prohibited in Sharia.
Thus, the main issue does not lie in the technology used, but in how the transaction system is operated and whether its benefits outweigh the potential losses caused.
Potential for Riba, Gharar, and Maysir in Digital Transactions
One of the issues that often arises in digital financial services is the potential for riba, which is the prohibited addition in certain transactions according to Sharia provisions.
In paylaterservices, for example, users are given the convenience of purchasing goods or services first and making payments at a specified time. Although it provides financial flexibility, this mechanism needs to be observed carefully, especially when there is interest on loans, additional fees, or payment terms that are not explained transparently.
It should be understood that loan interest and late payment penalties do not always have the same legal standing in fiqh muamalah.
The National Sharia Council of the Indonesian Ulema Council (DSN-MUI) Fatwa Number 17/DSN-MUI/IX/2000 regulates sanctions for customers who are capable but intentionally delay payments. In these provisions, sanctions in the form of fines can be applied as a form of ta'zir or disciplinary action with certain requirements, and the funds obtained are allocated for social purposes.
Meanwhile, customers who are unable to make payments due to force majeure beyond their control should not be subject to such sanctions. Therefore, the assessment of fines in digital financing services needs to consider the contract, the purpose of implementation, and the management of the collected funds.
Besides riba, the element of gharar or ambiguity also needs to be a concern. In the use of digital wallets, for example, users have the right to know administrative fees, service terms, transaction limits, and various risks that may arise.
When such information is not conveyed clearly, users are potentially at risk of loss due to ignorance of the agreed-upon terms.
Another issue arises in the trading of crypto assets, which carry high speculative risks. The decision of the 2021 Ijtima Ulama of the Indonesian Ulema Council Fatwa Commission VII stated that the use of crypto assets as currency is haram because it contains elements of gharar and dharar, and contradicts the currency provisions applicable in Indonesia.
Meanwhile, crypto trading as a commodity or digital asset is declared invalid if it contains elements of gharar, dharar, and qimar and does not meet the requirements as a commodity that can be traded according to Sharia.
However, crypto assets as a commodity can be traded if they meet the requirements of sil'ah, have supporting assets or a base value (underlying), and have clear benefits.
This shows that the assessment of digital assets needs to consider the characteristics of the asset and its transaction mechanism. Extreme price changes do increase risk, but they do not automatically make all transactions gambling without assessing the speculative elements involved.
Beyond contract issues, fraud through fake links, identity theft, and personal data leaks can also cause financial losses that contradict the goal of protecting wealth.
As a guideline, the DSN-MUI has issued Fatwa Number 116/DSN-MUI/IX/2017 regarding Sharia Electronic Money and Fatwa Number 117/DSN-MUI/II/2018 regarding Information Technology-Based Financing Services Based on Sharia Principles.
Both fatwas serve as important references for assessing the compliance of digital financial products and services with Sharia principles.
Analysis and Group View: Convenience Does Not Necessarily Bring Welfare
The development of digital transactions basically provides many benefits to the community. The presence of digital wallets and QRIS makes the payment process faster, more practical, and can help expand access to financial services, including for micro, small, and medium enterprises (MSMEs).
Business owners who previously only accepted cash payments now have more options to serve consumers. In addition, digital transaction records can also help with financial management if used properly.
From that perspective, digital payment technology has great potential to support economic welfare.
However, in our group's view, the convenience of digital transactions is not entirely proportional to the welfare felt by consumers.
The ease of obtaining financing through paylaterservices, for example, can encourage some users to make purchases without considering their financial capacity. If this habit continues, users risk accumulating debt and having difficulty meeting payment obligations.
On the other hand, unclear fees, the risk of personal data misuse, and digital fraud practices also have the potential to cause losses that conflict with the principle of hifzh al-mal.
Therefore, our group believes that the success of digital transactions should not be judged solely based on the convenience and speed of the service.
At least three important elements must be met to ensure digital transactions bring welfare.
First, justice. Every transaction must be carried out fairly without harming either party. Fees, margins, and payment terms need to be set reasonably and in accordance with the contract used.
Second, transparency. Service providers are required to provide clear information regarding transaction mechanisms, contracts, administrative fees, and the consequences if users do not meet payment obligations.
Third, consumer protection. Fund security, confidentiality of personal data, and the availability of complaint resolution mechanisms must be a major part of providing digital financial services.
These three elements are an important basis for assessing whether the development of financial technology is truly in accordance with the goals of Maqashid Syariah.
Thus, compliance with Sharia principles is not only seen from the existence of a service, but also from the mechanism, justice, security, and benefits produced for the community.
Efforts to Realize Digital Transactions in Accordance with Sharia Principles
To realize digital transactions that are in line with Maqashid Syariah, active involvement from the community, service providers, and supervisory institutions is required.
The community as users needs to improve digital financial literacy, especially in understanding contracts and terms before conducting transactions.
Users also need to get into the habit of reading service terms, considering financial capacity before using paylaterfacilities, and avoiding purchases that are not based on need.
In addition, personal data security must be a major concern. Users need to maintain the confidentiality of account information, not share verification codes with other parties, and be more careful with suspicious links or digital offers.
On the other hand, digital financial service providers have a responsibility to conduct business activities transparently and responsibly.
Information regarding contracts, administrative fees, interest or financing margins, and late payment terms needs to be conveyed clearly from the beginning. Service providers must also ensure system security and provide complaint handling mechanisms that are easily accessible to consumers.
Meanwhile, the Financial Services Authority (OJK) and Bank Indonesia (BI) have important roles in regulation and supervision according to their respective authorities. The DSN-MUI also plays a role in providing guidelines for product compliance and transaction mechanisms with Sharia principles.
Collaboration between parties is needed so that the development of financial technology is not only oriented toward transaction growth and economic profit, but also pays attention to justice and public protection.
Conclusion
The development of digital transaction technology is part of economic change that cannot be separated from the lives of modern society. The presence of digital wallets, QRIS, e-commerce, and digital financing services has provided various conveniences in daily economic activities.
However, technological progress also presents challenges, ranging from the potential for riba, gharar, and maysir in certain transaction mechanisms to the risks of consumerist behavior, fraud, and personal data leaks.
In the perspective of Maqashid Syariah, especially the principle of hifzh al-mal, the protection of wealth and user rights is something that cannot be ignored.
Our group believes that ideal digital transactions are those capable of combining technological convenience with the values of justice, transparency, and consumer protection.
Therefore, the community needs to be wise, honest, and responsible users of financial technology. The convenience of transactions should be utilized without ignoring Sharia provisions and individual financial capabilities.
Ultimately, the success of the digital economy is not solely determined by how fast transactions can be performed, but by the extent to which the technology provides benefits, maintains the security of wealth, and realizes common prosperity.
Comments 0
Write a Comment Share your response