

The author is an employee of the Rupiah Currency Management Implementation Unit at the Bank Indonesia Representative Office in Jember, East Java.
JurnalPost.com - When a storm hits, a captain does not always slow down the entire ship's engines. They can hold the rudder to keep the ship on course while increasing power to specific areas to ensure it continues moving toward its destination.
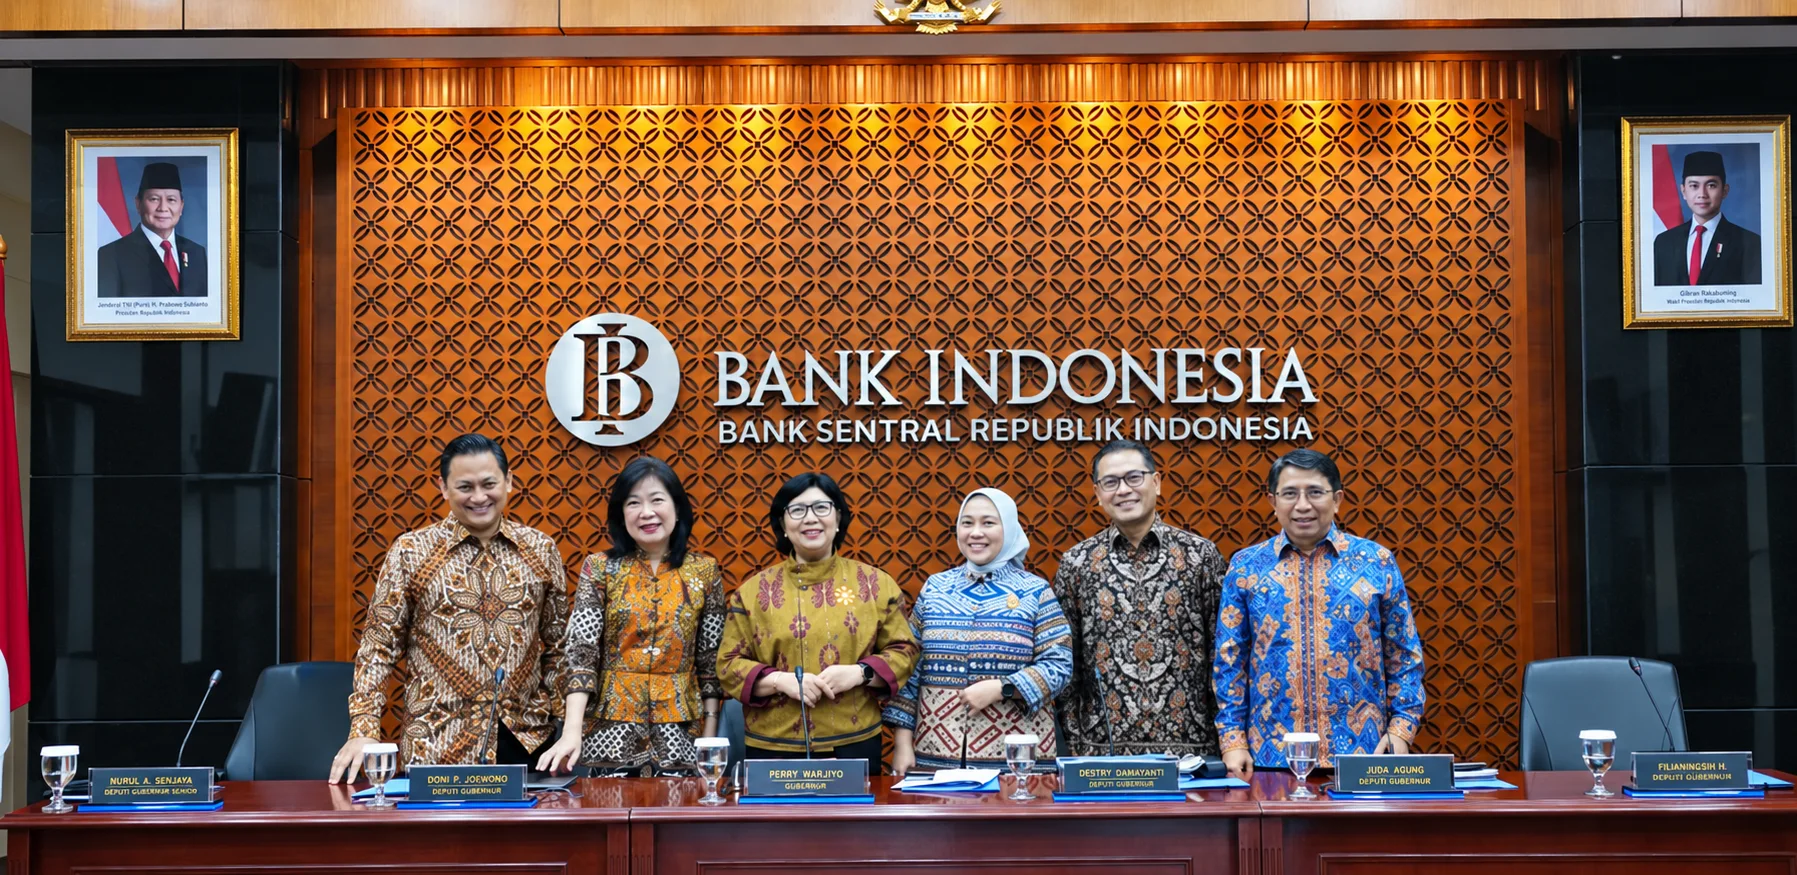
This analogy describes Bank Indonesia's decision during the Board of Governors Meeting on October 20–21, 2026, to maintain the BI-Rate at 5.75% amid global pressure, while simultaneously opening the liquidity tap through a reduction in the Statutory Reserve Requirement (GWM) and the strengthening of macroprudential incentive policies.
At first glance, these two steps appear contradictory. However, they are actually part of a strategy to maintain stability without allowing the engine of economic growth to lose power.
The decision to maintain the BI-Rate can be understood as an anchor protecting the Indonesian economy from external waves. Geopolitical tensions in the Middle East have kept global oil and commodity prices high. At the same time, the potential for U.S. interest rate hikes, high U.S. Treasury yields, and limited investor interest in emerging market assets have strengthened the U.S. dollar.
In such a situation, lowering interest rates too quickly risks widening yield differentials, triggering capital outflows, and increasing pressure on the Rupiah.
This pressure is not just a distant shadow. On October 20, 2026, the Rupiah was recorded at Rp17,985 per U.S. dollar, a depreciation of 0.61% compared to the end of September. In the third quarter of 2026, foreign portfolio investment also recorded a net outflow of 0.08 billion U.S. dollars.
Although the fourth quarter up to October 19 reversed to record a net inflow of 0.66 billion U.S. dollars, the direction of global capital can change very rapidly. Therefore, the 5.75% BI-Rate acts as a safety rail to keep Rupiah assets attractive while dampening further pressure on the exchange rate.
This cautious stance is also reflected in the decision to raise the Deposit Facility rate to 5.00%, while the Lending Facility rate remains at 6.50%. This means Bank Indonesia continues to strengthen monetary stabilization instruments without having to raise its benchmark interest rate.
However, maintaining the anchor does not mean the ship must stop. The domestic economy still requires fuel in the form of liquidity and financing.
This is where the reduction in the Statutory Reserve Requirement (GWM) becomes important. The GWM for conventional commercial banks is being lowered in stages from 9% to 7%, while the GWM for sharia commercial banks and sharia business units is dropping from 7.5% to 5.5%. The reduction is being carried out in two stages in November and December 2026.
Like a dam, Bank Indonesia is not opening all the gates, but rather adjusting the flow so that more water can reach productive channels.
This additional liquidity is needed because there is a disparity between the surge in credit demand and the growth of banking funds. Credit in September 2026 grew by 13.26% year-on-year, while Third-Party Funds (DPK) only grew by 8.22%.
Investment credit even surged by 23.20%, working capital credit by 11.89%, and consumer credit by 4.86%. If this gap is left unaddressed, banks could face increasingly tight liquidity space.
The reduction in GWM provides additional breathing room so that banks can maintain their intermediation function without having to wait for deposit growth to catch up with financing needs.
Nevertheless, opening the tap does not necessarily mean water will flow to the fields. Banks still have unused loan facilities (undisbursed loans) amounting to Rp2,562.57 trillion, equivalent to 21.70% of the available credit ceiling.
This figure shows that the financing problem lies not only in the availability of funds but also in credit demand, business viability, risk perception, and the confidence of economic actors.
Therefore, additional liquidity must be accompanied by improvements in the business climate and the quality of projects so that funds do not simply settle on bank balance sheets.
Bank Indonesia is attempting to direct this flow through the Macroprudential Liquidity Incentive Policy (KLM). As of the first week of October 2026, KLM incentives reached Rp458.5 trillion, consisting of Rp336.4 trillion for financing channels and Rp122.1 trillion for money market deepening.
Starting in December 2026, the KLM limit will be adjusted from 6% to 5%, with a maximum financing incentive of 3% of DPK and a maximum money market deepening incentive of 2%.
This adjustment is not just a change in the amount of incentives, but a strengthening of policy direction so that liquidity is more effective in supporting productive financing and money market deepening.
The tap, therefore, is not being opened without direction. The flow is aimed at sectors capable of creating jobs, driving productive activities, and strengthening liquidity redistribution among banking players.
This easing also does not mean Bank Indonesia is ignoring inflation. September 2026 inflation was recorded at 3.28% year-on-year, still within the 2.5±1% target range.
Core inflation even declined to 2.84%, although volatile food inflation rose to 5.03% due to weather disruptions in several production centers.
This situation is like a doctor seeing a patient whose condition is quite stable but not yet entirely risk-free. The monetary policy dosage is maintained, while support for economic circulation is provided through more targeted instruments.
This two-handed strategy is also visible in the Rupiah stabilization policy. Bank Indonesia is optimizing interventions in the spot market, Non-Deliverable Forward (NDF) offshore, and Domestic Non-Deliverable Forward (DNDF) onshore, while simultaneously increasing hedging incentives for foreign funding.
Since being implemented in June 2026, this incentive policy has successfully attracted foreign capital inflows of 9.9 billion U.S. dollars as of October 20, 2026.
Foreign exchange reserves of 146.3 billion U.S. dollars at the end of September also provide a buffer equivalent to 5.3 months of imports. This means external defenses are strengthened without closing the door to domestic economic financing.
The next challenge is to ensure that liquidity truly transforms into production, jobs, and income.
Economic growth in 2026 is projected to be in the range of 4.9–5.7%, supported by household consumption, government investment, the beginning of strengthening private investment, and non-oil and gas exports.
However, liquidity is merely a lubricant, not the engine itself. Without viable projects, policy certainty, strong consumption, and the courage of the business world to expand, additional funds may circulate in the financial sector without fully flowing into the real sector.
Therefore, maintaining the BI-Rate while opening the liquidity tap is not a contradictory policy.
The BI-Rate acts as a brake to keep the Rupiah and inflation under control, while the reduction in GWM and the strengthening of KLM act as the gas pedal that keeps financing moving.
The challenge lies in the ability to press both with precision. Braking too hard can weaken growth, but pressing the gas too deeply can increase risks to stability.
Amid the slippery road of the global economy, the success of this policy mix will be determined not by how wide the tap is opened, but by how accurately liquidity is channeled toward productive activities.



Comments 0
Write a Comment Share your response